Home loan declined? What first home buyers can look at next
20 October 2026 3 min read
Being told no on a home loan stings, especially after years of saving. A decline is about one application at one point in time, and the reason behind it is usually the best guide to what you can look at next. The most useful thing you can do is find out why it happened, then look at what could change before you try again.
Your next step
If you'd like help making sense of a decline, we can connect you with someone who can talk through your options, with no obligation.
It takes about 90 seconds, then we put you in touch with someone who can talk through your options, and there's no credit check to enquire.
Key points
- Ask the lender why it declined, because the reason shapes everything that comes next.
- You can ask each of New Zealand's three credit reporting agencies for a copy of your credit report, and the government's govt.nz site explains how.
- Common reasons for a decline include the deposit, income, spending, credit history or the property itself.
- Applications can show up on your credit record, so applying everywhere at once isn't always helpful.
Why do first home loans get declined?
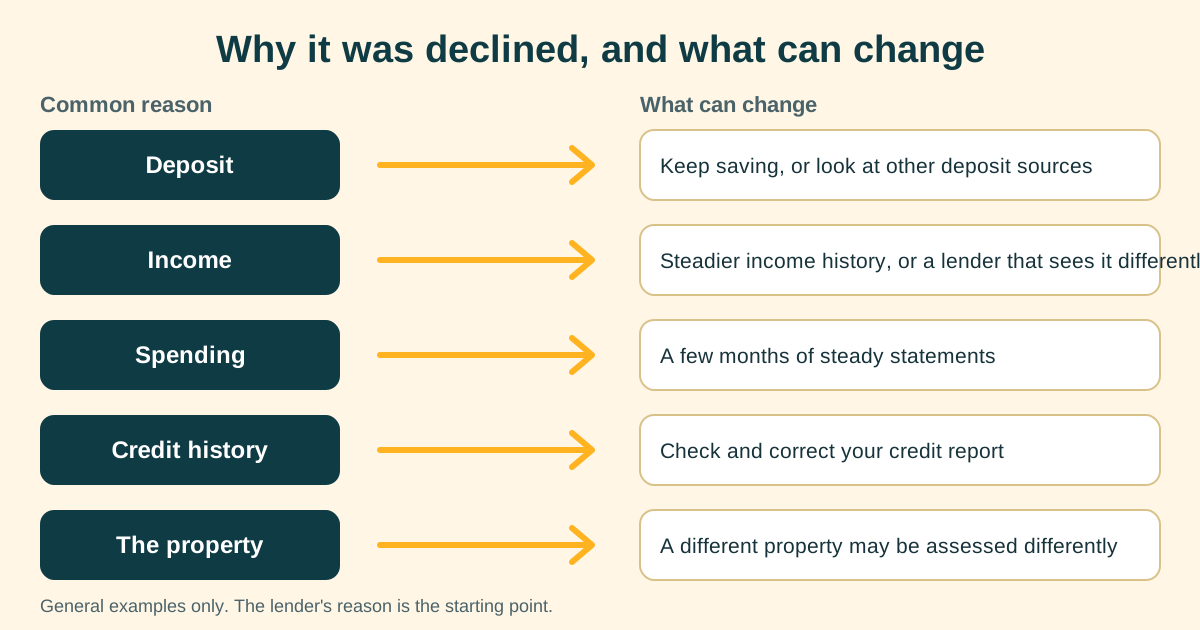
Lenders have to be satisfied a loan is likely to be affordable and suits your needs, so they look closely at your whole picture. The usual reasons are:
- Deposit: it falls short of what that lender needs for that type of property.
- Income: it doesn't stretch to the repayments at the lender's assessment rate, or it's new, irregular or hard to verify, such as a recent job change or self-employed income.
- Spending: recent bank statements show outgoings that look high next to your income.
- Credit history: missed payments, defaults or a lot of recent credit applications.
- The property: some apartments, small units, unusual titles or homes needing big repairs are assessed more cautiously.
What should I do first after a decline?
- Ask the lender to explain the main reason, and write down exactly what they said while it's fresh.
- Get your credit reports from Centrix, Equifax and Experian, and ask for anything wrong to be corrected.
- Look over your last few months of statements the way a lender would, and note anything that might raise a question.
- Recheck your numbers, including how much KiwiSaver you may be able to withdraw and whether a Kāinga Ora First Home Loan could fit your situation.
Can a different lender see it differently?
Sometimes, because each lender sets its own criteria, so a no from one doesn't automatically mean a no from all of them, and some look at things like self-employed income, a smaller deposit or a recent job change in their own way. Before you house hunt again, pre-approval can give you a clearer picture. Getting pre-approval takes about 5 to 10 working days as a guide. Once you have it, it's usually valid for 90 days, but it pays to check with your lender.
What if my credit history is the problem?
Errors on credit reports do happen, and you can ask each credit reporting agency to correct them, while the organisation that supplied the information has to look into it. Genuine past issues tend to matter less as time goes on and you build a steady record of paying on time. Our page on buying a first home with bad credit goes into this in more detail.
How long should I wait before applying again?
There's no set rule, because it depends on the reason. A deposit gap might mean a few more months of saving, while a spending question might just need a stretch of steady statements. If the issue was the property, the next application could happen as soon as you find a different home.
Home loan declined FAQs
Does a declined home loan hurt my credit score?
Credit applications can be recorded on your credit file, and several in a short time may make a lender more cautious. Checking your own credit report doesn't count against you, because it isn't a credit application.
Can I still use my KiwiSaver after a decline?
A decline on its own doesn't change whether you meet the KiwiSaver first-home withdrawal rules, and your provider checks those when you apply.
Will the lender tell me why I was declined?
You can ask the lender to explain the main reason your application was declined, and it's worth noting down what they say.
Can someone help me understand my options?
Yes. We can connect you with someone who can talk through your options and what different lenders tend to look at.
If you'd like help making sense of a decline, we can connect you with someone who can talk through your options, with no obligation.
General information only, not advice. We're a referral service and may receive a commission.
Sources (checked 19 October 2026):
- Consumer Protection (MBIE): What lenders must do, affordability and suitability checks
- Consumer Protection (MBIE): Credit checks, scores and history, credit reports, correcting errors and credit enquiries
- govt.nz: Check your own credit record, the three agencies and how to request a report
- Centrix: requesting your own report doesn't affect your score
- Kāinga Ora: First Home Loan
- govt.nz: Financial help for first-home buyers
Reviewed against Consumer Protection, govt.nz, Centrix and Kāinga Ora.
Related reading